
Look at the way we create money, and you’ve got to wonder whether our species is really as intelligent as we think. Understanding how banks create money is crucial for grasping our financial system.
In an earlier post, I explained that around 98% of our money is created by commercial banks, which then charge interest on it. That is extraordinary. The result—combined with our land tenure system—is a built-in growth imperative and a widening gap between net lenders and net borrowers.
This exploration of how banks create money reveals the intricacies of our economy and its impact on society.

How the Government Created Money During COVID — And Why It Was Still Flawed
In emergencies like COVID, when big money is involved, the government uses another equally questionable way to create money.
There are two key public institutions involved:
1. The Reserve Bank (RBNZ) can create notes and coins and spend them into existence. It can also create digital money—without physically printing anything—and record it electronically.
2. The Treasury issues government bonds. In this system, citizens, banks, and institutions (local or foreign) lend money to the government and receive regular interest payments until the bonds mature, at which point the principal is repaid.
Now comes the more absurd part.
During Covid, the Treasury issued bonds—but who bought them? The Reserve Bank.
Through what was called Quantitative Easing, or the Large-Scale Asset Purchase (LSAP) programme, the RBNZ created money and used it to buy government bonds—around $53 billion in total.
So effectively, one arm of government created money and lent it to another arm of government—at interest.

This was the $53 billion that helped keep businesses solvent and workers able to pay their living costs during lockdowns. The outcome mattered. But the mechanism? Peculiar.
Because when you hold government bonds, you receive interest. So the Treasury ended up paying interest to the Reserve Bank—money it didn’t need. If an institution can create money, why would we pay it interest?
What Is Direct Monetary Financing and How Could It Replace Debt-Based Money?
There is a better way.
In New Zealand (and the UK), the organisation Positive Money has long advocated for Direct Monetary Financing (DMF). Under this model, the Reserve Bank would fund a portion of government spending directly—creating money and transferring it to the Treasury without the detour through bond markets.
In other words: spend money into existence for public purposes, without creating debt.
Has this been done before? Yes.
Between 1935 and 1979, the Reserve Bank of New Zealand funded state housing, industrial development, and infrastructure through controlled credit creation. Over the same period, the Bank of Canada financed major public works without increasing sovereign debt.
So this is not radical—it’s historical.
Of course, safeguards are essential. Any use of DMF must include constraints to avoid inflation. But those design questions are solvable, and well covered in existing proposals.
Complementary Currencies: Real-World Examples of Interest-Free Money Systems
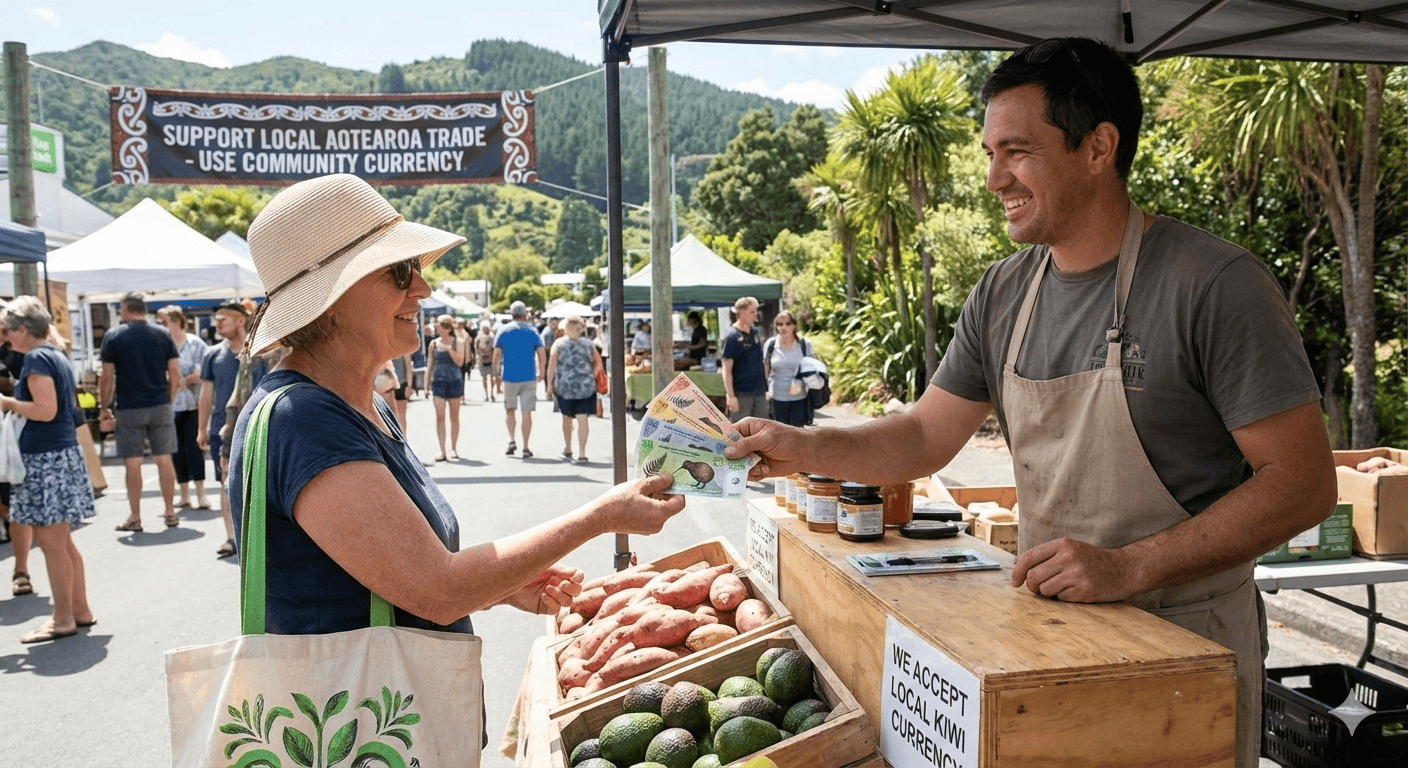
In my 2005 book Healthy Money Healthy Planet, I described a range of complementary currencies that create money directly and put it into circulation.
One of the most famous examples was in Wörgl, Austria, during the Great Depression. In 1932, the town issued its own currency with a negative interest rate to encourage spending and discourage hoarding. The result was a burst of local economic activity.

The mayor had been inspired by Silvio Gesell, who argued that money should function as a tool for exchange, not accumulation—likening ideal currency to something that loses value over time, much like perishable goods.
It’s a striking idea: money as a tool for exchange, not accumulation.
Can Public Finance Help Solve the 2026 Fuel Crisis Without Locking In Fossil Fuels?
Would Direct Monetary Financing be appropriate in the context of the 2026 fuel crisis? Yes—but with care.
We are now in a world shaped by war and climate instability. The last thing we want is to lock in fossil fuel dependence or worsen emissions.
For example, Ho Chi Minh City in Vietnam plans to spend around $280 million annually to make bus travel free. That reduces emissions while easing pressure on fuel supplies—a smart use of public funding.

Of course, essential services—ambulances, fire services, hospitals—must have reliable fuel supplies. But that support should be temporary and paired with strong incentives to electrify vehicle fleets. DMF could help finance that transition.
Unfortunately, what we are seeing globally is the opposite: governments subsidising fossil fuels.
One striking example came just a week into the Iran war, when Malaysia increased its fuel subsidy dramatically—from RM700 million to RM3.2 billion. That is a massive escalation in support for fossil fuel consumption.
Australia, meanwhile, cut fuel excise taxes by about 30 cents per litre.
These policies may provide short-term relief, but they entrench long-term problems.
Rethinking Money Creation: Why Interest-Free Public Finance Is the Way Forward
We have the institutional tools to create money differently—more directly, more transparently, and more intelligently.
The question is not whether we can afford to do so.
It is whether we can afford not to.


Hi Deirdre,
This is what I wanted to talk to you about.
You are missing a few details and I can show you what they are.
It goes back to what Prof Richard Werner stated -banks do not make loans, they purchase securities.
Please contact me directly at my email address, I can show you the issues.
Yes I have now looked up Richard Werner’s 2014 paper. Looks like the stages and amount have names. Busy today but might contact you tomorrow. Deirdre