Empowering Communities Through Shared Savings
Discover the Power of Savings Pools
Join a community-driven initiative where financial independence meets collective support. Explore how savings pools can transform your financial future.
Understanding Savings Pools
Savings pools, a model developed by Living Economies New Zealand. also known as the genuine wealth system, are informal private groups where members pool their savings for mutual benefit. These groups allow participants to contribute varying amounts, either as lump sums or through regular savings. The pooled resources are then available for members to access as interest-free loans, promoting financial support and reciprocity within the group. By fostering a culture of trust and cooperation, savings pools offer a sustainable alternative to traditional banking, empowering members to build wealth collectively.
For an excellent introduction to savings pools, read this article by Frith Chamberlain published in Organic NZ Magazine
Benefits of Joining a Savings Pool
Security
The security that comes with investing in one another instead of making bank deposits, and being part of a group where everyone is committed to helping each other out
Interest-Free Loans
Access funds without the burden of interest, allowing you to manage your finances more effectively.
Collective Wealth Building
Enhance your financial security by participating in a system that prioritizes community growth and support.
Reciprocity in Lending
Experience a lending system where your repayments help others, fostering a cycle of mutual aid.
Community Support
Be part of a supportive network that extends beyond financial assistance, offering shared resources and collaboration.
Savings pools require good communication, cooperative decision-making, and mutual commitment. If you aspire to develop these qualities, you may find that a savings pool is a good tool. Your savings pool can include members who do not have any money to contribute at the outset.
Discover How Savings Pools Operate
Step 1: Member Contributions
- Each member (or household) chooses how much to save with the group.
- Contributions remain personally owned, but may be temporarily unavailable if used for group loans.
- These pooled funds form the basis for mutual support and lending.
Step 2: Loan Requests
- Members may request a loan from the pool and propose their own repayment schedule.
- The group collectively decides whether to approve each request.
- For larger loans, the group may ask for security or collateral.
Step 3: Repayment & Reciprocity
- Borrowers repay the loan principal as agreed.
- In addition, they deposit “reciprocity savings” into the pool for a set time.
- These reciprocity savings help sustain the pool and enable future borrowing by others.
Reciprocity: Mutual Empowerment Through Interest-Free Lending
Learn About Reciprocity
Understanding the Power of Fair Exchange
The Essence of Reciprocity
In Short
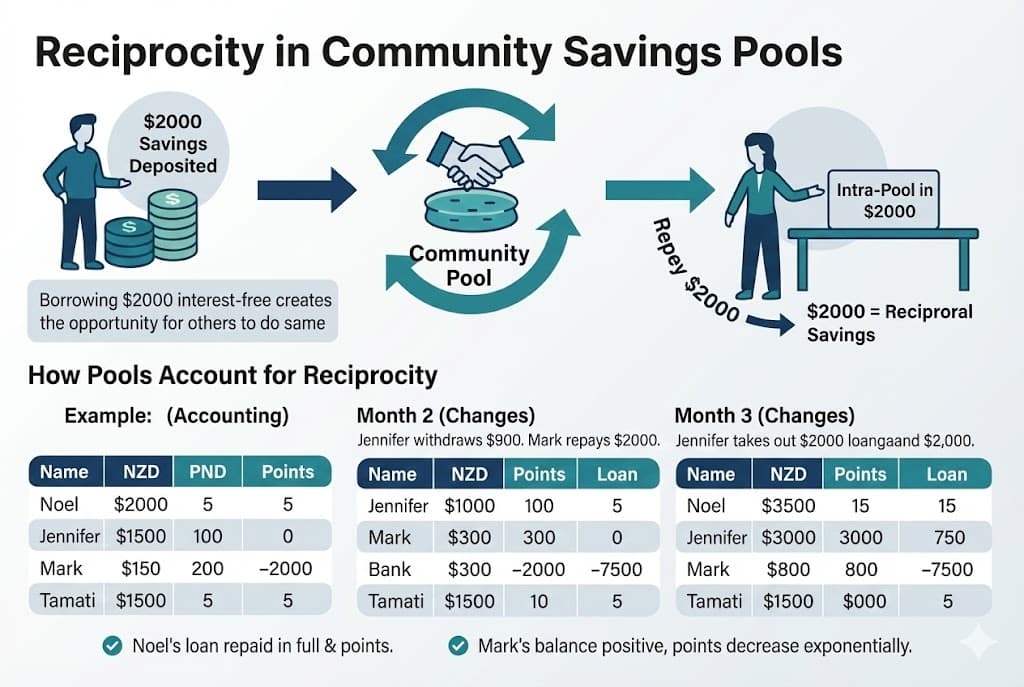
Reciprocity means “fair exchange.” In a Savings Pool, if you borrow money interest-free, you agree to let others borrow your savings later. It’s a cycle of giving and receiving.
How it Works (The Points System):
-
Savings (+): Every dollar you save earns you positive points.
-
Loans (-): Every dollar you borrow creates negative points.
-
The Goal: Over time, aim to balance your points back to zero. This ensures everyone gets a turn to use the money.
The Essence of Reciprocity
Why Reciprocity Matters in Savings Pools
Reciprocity is the backbone of successful savings pools, fostering trust and cooperation among members. By contributing to the pool, members not only secure financial support for themselves but also empower others within the community. This mutual aid system ensures that resources circulate effectively, benefiting everyone involved.
In a savings pool, reciprocity encourages members to support one another through shared financial responsibilities. This system builds a strong network of trust, where each member’s contribution is valued and reciprocated, creating a sustainable financial ecosystem that supports both individual and collective growth.
The Scenario: Imagine 4 members:
Real-Life Example: 4 Members, 4 Different Stages Let’s watch how the Points System works for four different members—Jennifer, Mark, Noel, and Tamati—over a few months.
1. Jennifer: The Saver
Status: $500 Savings | Points: High Positive Jennifer has been saving for months. Because her money has been available for others to borrow, she has built up a massive “points credit.” Even if she withdraws some cash for a holiday, her points stay high, meaning she is in a perfect position to ask for a large interest-free loan whenever she needs it.
2. Mark: The Borrower
Status: $1,200 Loan | Points: High Negative Mark used the pool to pay off a high-interest credit card. While he is debt-free from the bank, he now owes “reciprocity” to the pool. Even after he pays the $1,200 back, he will likely stay in the pool as a saver for a while to bring his points back to zero.
3. Noel: The Reciprocator
Status: $2,000 Savings | Points: Low Negative Noel has already paid back her loan in cash, but she still has negative points from that past loan. She is now “paying it forward” by keeping $2,000 of her own savings in the pool. This allows other members to borrow her money, which quickly earns her the points she needs to clear her balance.
4. Tamati: The Balanced Member
Status: $0 Balance | Points: Positive Tamati is the “ideal” member. He saved money first, then took a small loan and paid it back. Because he saved before he borrowed, his points never stayed negative for long. He currently has no debt and a healthy points balance, ready for his next community project.
| Member | Cash Status | Points Status | What this means |
| Jennifer | 🟢 Has Savings | 🟢 Positive | She is helping the pool grow. She is ready to borrow anytime. |
| Mark | 🔴 Has a Loan | 🔴 Negative | He is using pool funds. He must repay the cash and later save to fix his points. |
| Noel | 🟢 Has Savings | 🔴 Negative | She is “paying it forward.” She must leave her savings in the pool until points recover. |
| Tamati | ⚪ Zero Balance | 🟢 Positive | He borrowed and repaid. Because he saved earlier, he is perfectly balanced. |
Most pools maintain a shared bank account that requires multiple signatories. They also hold regular in-person meetings, such as shared dinners, and have established channels for communication between gatherings.
Learn bout Pool Administration
How are savings pools administered?
- pools operate transparently, and all decisions are made jointly by the pool members, with everyone having an equal say in loan agreements and other pool decisions
- pools require written confidentiality agreements from all members at the time they join the pool
- pools, in exceptional circumstances, might give a dissenting member the option of opting out of a particular loan, so that the dissenting member neither blocks a loan going forward nor participates in its risks
- pools require a mutually agreed form of security against loans, especially larger loans
- pools might purchase an item on behalf of a member, and own the item until the loan has been repaid in full
- pools require written (legally-enforceable) loan agreements
- A pool volunteer keeps the above records without payment
- pools open a shared bank account for a few volunteers, allowing all members to deposit and requiring two signatories for withdrawals
- pools keep any bank interest (if any) to defray any operating costs of the pool, rather than distributing it to any member as income
- A pool volunteer (or rotating team of volunteers) provides all members with monthly statements of each member’s savings, loan, and reciprocity points balances
- pools measure reciprocity commitments with a simple points system, with point credits given on a monthly basis whenever members have a positive balance (savings) and points debited each month when members have a negative balance (loans)
- pool members can withdraw their own savings at any time simply by notifying other pool members, provided that (1) the money is currently available instead of tied up in loans, and (2) the member does not have any outstanding reciprocity agreements
- pools usually do their own accounting and administration, perhaps in a simple spreadsheet, and software is also available
What is the history of savings pools?
Precedent
For centuries, people have recognised the benefit of pooling their resources. Examples from the last century include co-operatives, buyers’ clubs, investment syndicates and the like.
Living Economies’ approach to savings pool is a model adapted from the very successful Swedish JAK Bank, which has been providing its members with interest-free loans for over fifty years.
Savings pools in Aotearoa New Zealand
The Aotearoa New Zealand approach has been developed by Living Economies Educational Trust, following a visit by Board Trustee Bryan Innes to the JAK Bank. At first, Bryan called this approach the “Genuine Wealth System” to highlight one of the core value principles of savings pools, which is that people find wealth within community, not in a bank. For whatever reason, however, the name ‘savings pools’ is the one that’s found a place in the media.
There are now successful savings pools all around New Zealand. Since 2009 people have paid off cars, loans, and credit cards. They’ve funded travel and made essential house modifications. They’ve even paid off mortgages!
Success Saving Pools Stories
Organic NZ Magazine has published an excellent introduction to savings pools, written by Frith Chamberlain, the Chairperson of Soil & Health’s Mid Canterbury Branch. Frith participated alongside many of our Trustees in a November 2017 Savings Pool hui, hosted by Awhi Tautoko Trust.
We encourage you to read Frith’s article.
Alongside providing a solid explanation of savings pools, the article shares Frith’s own experiences in a savings pool. We’ve decided to take a page from his book and share additional personal stories from pool participants across NZ. Stories are anonymised to preserve pool confidentiality.
P’s story
My introduction to Savings Pools took place at a public meeting in March 2013.
The idea sounded innovative and I loved the concept of being able to have access to interest-free funds and also to support others to have this same access.
What finally sold me was the ‘group consensus decision-making policy’ that offered me security, inasmuch as nothing could happen to the fund unless I agreed. So it was with a sense of apprehension and also adventure that I joined with 12 others, some of whom I’d met in passing and others whom I’d not previously met, and we agreed to form a group. I started depositing small amounts of excess money into the shared bank account to see how it would go while not risking too much.
It soon became apparent that participating in our Savings Pool had some unanticipated spin-offs.
At the time I was experiencing huge stress with credit card debt of up to $30,000 accumulated over the years, and for the first time I am now credit card free! Where I used to pay interest on loans (credit cards) to purchase essentials (medical bills) and non-essential goods and services (fab shoes) I can now access non-interest bearing funds and be self-disciplined in my spending and saving.
I now choose to save into the pool (instead of the bank), but because I have to apply and get agreement to draw out funds (never any problem), I am no longer subject to the impulse buying of the plastic cards.
This year I formed a second pool with my children and grandchildren. Together we look forward to a future free of the crippling effect interest has had on our lives. As a family we’ve become closer and more supportive of each other than ever before. There’s now trust and respect that didn’t have an opportunity to grow when we lived such separate lives, each dealing with financial stress independently.
I find it immensely satisfying that Savings Pools have been a doorway to my financial freedom and that I’m now able to support and contribute to the financial freedom of others.
B’s story
In May 2013, I heard of a Savings Pool through Living Economies and the Green Dollars association I belong to. I had done the round of the banks trying to consolidate my debt and had been turned down by them all. My life had become a downward spiral of escalating debts. A divorce followed by a tragic family loss had escalated the emotional turmoil and hardship I found myself in. All felt hopeless until I attended the first meeting of the newly formed Savings Pool.
After introducing myself, I mentioned upfront that I had neither savings nor money available to contribute to the pool and due to my present situation was actually looking for a loan to get out of debt.
A week later, the group had not only agreed to my joining but also lent me $12,000.00 allowing me to get rid of my credit card debt in full, the balance of my car repayments and some major outstanding bills. In return my car was accepted as security while I continued to drive it and I started repaying to the Savings Pool the amount of money I had been paying the finance company for my car – a single shift of where my money was going.
I felt such relief and was smiling from ear to ear when I left the bank after paying all those debts off and when I met one of the group that day, was told it had been a privilege to have been able to help and how good it felt for the group to have been able to contribute to my improved situation.
I had not realised at the time this situation could be seen from that angle. Being the happy receiver of such help when you are in need always feels good, even when it is quite hard to ask for it in such difficult circumstances. It was a totally new concept to me that it could feel so good for others to be offered the opportunity to help.
This emotional link created through the act of lending and borrowing between friends was truly gratifying for both parties and an unexpected benefit of being part of the group.
It turned out for me that being a member of the Savings Pool has not been just about the money but also about making new friends, sharing ideas and resources, brainstorming practical solutions together. It felt very supportive and I am highly grateful to have been accepted as part of the group.
The cherry on top of the (already iced!) cake is that at the end of repaying my interest-free loan, I will have accumulated a similar amount in savings – something that would have been impossible while I was in debt. So while helping myself, I am also helping others, as my loan repayments and savings contributions are made available to the pool, to lend to someone else right away.
This is a very satisfying system as it gives me a sense of instantly being able to pay it forward, when I had nothing to contribute originally. A truly win-win and uplifting situation.
S’s story
I was introduced to savings pools by some good friends who were members themselves. They explained that the savings pool was a great way to help one another with cashflow and money matters.
I loved the idea, as I grew up in a small European community where funds were lent and borrowed freely, which worked great and brought the community together. I also liked the idea of talking about money freely as I would with my family (who still live in Europe).
The savings pool helped me start my business.
Soon after I joined, I received an interest-free loan of $10,000.00 for starting my dream business. This loan was backed by the stock of products that I bought with the business.
I was impressed by the ease and openness of the group, and the legally correct process it followed. I felt very good being able to start my business on terms that felt human and caring rather than dictated through an impersonal banking process.
That was two years ago. My business has since reached an annual turnover of $1.5M, exporting products into over 30 countries and growing steadily. I am very grateful to have such caring supporters from the savings pool.
Legislation applicable to savings pools
Depending on how a savings pool operates, it might need to comply with some or all of the statutes listed below.
- If the Savings Pool is carrying on a business of providing or offering to provide a financial service (providing loans is a “financial service”) then the Savings Pool needs to register as a financial services provider under the Financial Service Providers (Registration and Dispute Resolution) Act 2008.
- If the Savings Pool undertakes financial activities in the “ordinary course of business” it might be required to comply with the Anti-Money Laundering and Countering Financing of Terrorism Act 2009.
- A loan is a “credit contract”. The Credit Contracts and Consumer Finance Act 2003 could apply if the lender (the Savings Pool via its members) carries on a business of providing credit.
- Members of an existing Savings Pool, or people proposing to form a Savings Pool, could be “financial advisers” for the purposes of the Financial Advisers Act 2008 if they provide financial advice “in the ordinary course of a business“.
- Savings Pool members – particularly the persons in whose name the Savings Pool’s bank account is held, and who hold the funds on trust for the members – could be subject to broker provisions of the Financial Advisers Act 2008, and also to the Financial Advisers (Custodians of FMCA Financial Products) Regulations 2014, if they are carrying on a business of providing or offering to provide custodial services to a client.
- Last, but not least, the Financial Markets Conduct Act 2013 could apply if a Savings Pool has not ensured that each member’s funds are held on trust for the relevant member. (If each member’s funds are not held on trust for the relevant member, the pooling of members’ funds could be regarded as the issue of debt securities by the Pool, which would then have to comply with the disclosure obligations in the FMC Act unless it could rely on one of the available exemptions. There are exemptions for offers to relatives and close business associates, and – so long as certain conditions are met – for “small offers”, but even if it can rely on those exemptions, the FMC Act will restrict how a Savings Pool can operate. Accordingly, each Savings Pool should seek its own legal advice, and ensure that whatever amount a member pays into the Pool’s account – excluding any loan repayment – remains owned by that member.)
Further reading (Available at our shop)
- Healthy Money, Healthy Planet, by Living Economies co-founder Deirdre Kent. A New Zealand look at how our money system drives debt and what interest-free alternatives, savings pools among them, can do instead. Available at our shop.
What is reciprocity?
‘Reciprocity’ is the practice of accounting for how long it takes someone to repay a loan and asking them to make savings available to others for the same length of time. In Living Economies’ experience with pools throughout the country, reciprocity is essential to keep savings pools going beyond the initial enthusiasm that accompanies a start-up. It’s worth reading about this in more detail.
Are savings pool loans truly interest-free?
Yes, that’s right: no interest.
Are savings pools legal?
Yes. A savings pool is simply a group of people who choose to save and lend money to each other — there is no New Zealand law that prevents this. Because savings pools are informal groups rather than registered financial entities, they operate outside the regulatory framework that applies to banks and finance companies. The key is to keep the pool unregistered.
Living Economies can provide general information about applicable legislation, but pools are advised to seek their own legal advice when their specific circumstances require it.
Further reading: Money Creation in New Zealand — Reserve Bank of New Zealand
Who can set up a savings pool?
Anyone can. Savings pools can be formed by a group a friends, a family, or any group of like-minded people. Living Economies can offer assistance.
How can I join a pool
Living Economies might be able to provide contact information for savings pools in your area, but it does not recommend or endorse any particular savings pool, and it is for each savings pool to decide whether to invite new people to join.
What is demurrage in local currencies?
Demurrage is a system where the value of the currency decreases over time, encouraging quicker circulation and trade.